Life has a funny way of producing unexpected expenses at exactly the wrong time.
The car needs a major repair. The hot water system stops working. The fridge dies. You have an unexpected medical bill. Or perhaps your income suddenly drops.
Having money set aside for these situations can make a huge difference.
But how much should you actually keep in an emergency fund?
You’ve probably heard the advice that you should have three to six months of expenses sitting in cash.
While that can be a useful starting point, the right amount for you depends on your circumstances.
What is an emergency fund?
An emergency fund is money you've deliberately set aside to deal with unexpected financial events.
It isn't your holiday fund.
It isn't money you've put aside for a new car.
And ideally, it isn't money you need to use for your normal monthly expenses.
It's there for the things you didn't plan for.
The purpose isn't necessarily to earn the highest possible return. It's to give you access to money when you need it, without having to rely on a credit card, personal loan or selling investments at an inconvenient time.
So, is three to six months enough?
For some people, absolutely
For others, it may not be.
Consider a couple with two stable incomes, relatively low debt and secure employment. Their financial position may be very different from a single-income family with a large mortgage and young children.
A useful starting point is to work out your essential monthly expenses.
Think about things such as:
- Mortgage or rent
- Groceries
- Utilities
- Insurance
- Transport
- School or childcare costs
- Loan repayments
- Other essential household expenses
You can then consider how many months of those expenses you'd want covered if your circumstances changed.
The important point is that you're not necessarily trying to replace your entire lifestyle for six months.
You're trying to make sure your family can continue meeting its essential commitments while you work out what comes next.
Your job security matters
The stability of your income is another important consideration.
If you're in a highly secure role with a predictable income, you may feel comfortable holding a smaller emergency reserve.
If your income is variable, you're self-employed, work on a contract basis or work in an industry where employment can be less predictable, you may prefer a larger buffer.
Similarly, a business owner may need to think about personal and business cash reserves separately.
There's no universal number that works for everyone.
Don't forget about your mortgage
For many Australian households, the mortgage is their largest monthly commitment.
If you're carrying a significant home loan, having an adequate cash buffer can provide valuable peace of mind.
Some people may also consider using an offset account as part of their emergency cash strategy.
An offset can potentially reduce the interest charged on your home loan while keeping the money accessible.
However, the right approach depends on your loan structure, interest rate, financial goals and overall circumstances.
The important thing is that your emergency money remains accessible when you need it.
What about your investments?
You might think:
“I've got $50,000 invested, so why do I need an emergency fund?”
The problem is that investments aren't necessarily designed for short-term emergencies.
Markets can fall, sometimes significantly.
If you suddenly need money during a market downturn, you could be forced to sell investments when their value is lower than you'd like.
Having a separate cash reserve can give your longer-term investments time to do their job without being interrupted by an unexpected expense.
What if I don't have an emergency fund yet?
Don't let the idea of needing several months of expenses put you off.
You don't need to build the perfect emergency fund overnight.
Start with something.
Perhaps your first goal is $1,000.
Then $2,500.
Then one month's essential expenses.
You can gradually build towards a level that makes sense for your circumstances.
Automating a regular transfer into a separate savings or offset account can make this much easier.
Even a relatively small amount each payday can add up over time.
The bigger picture
An emergency fund is just one part of being financially prepared.
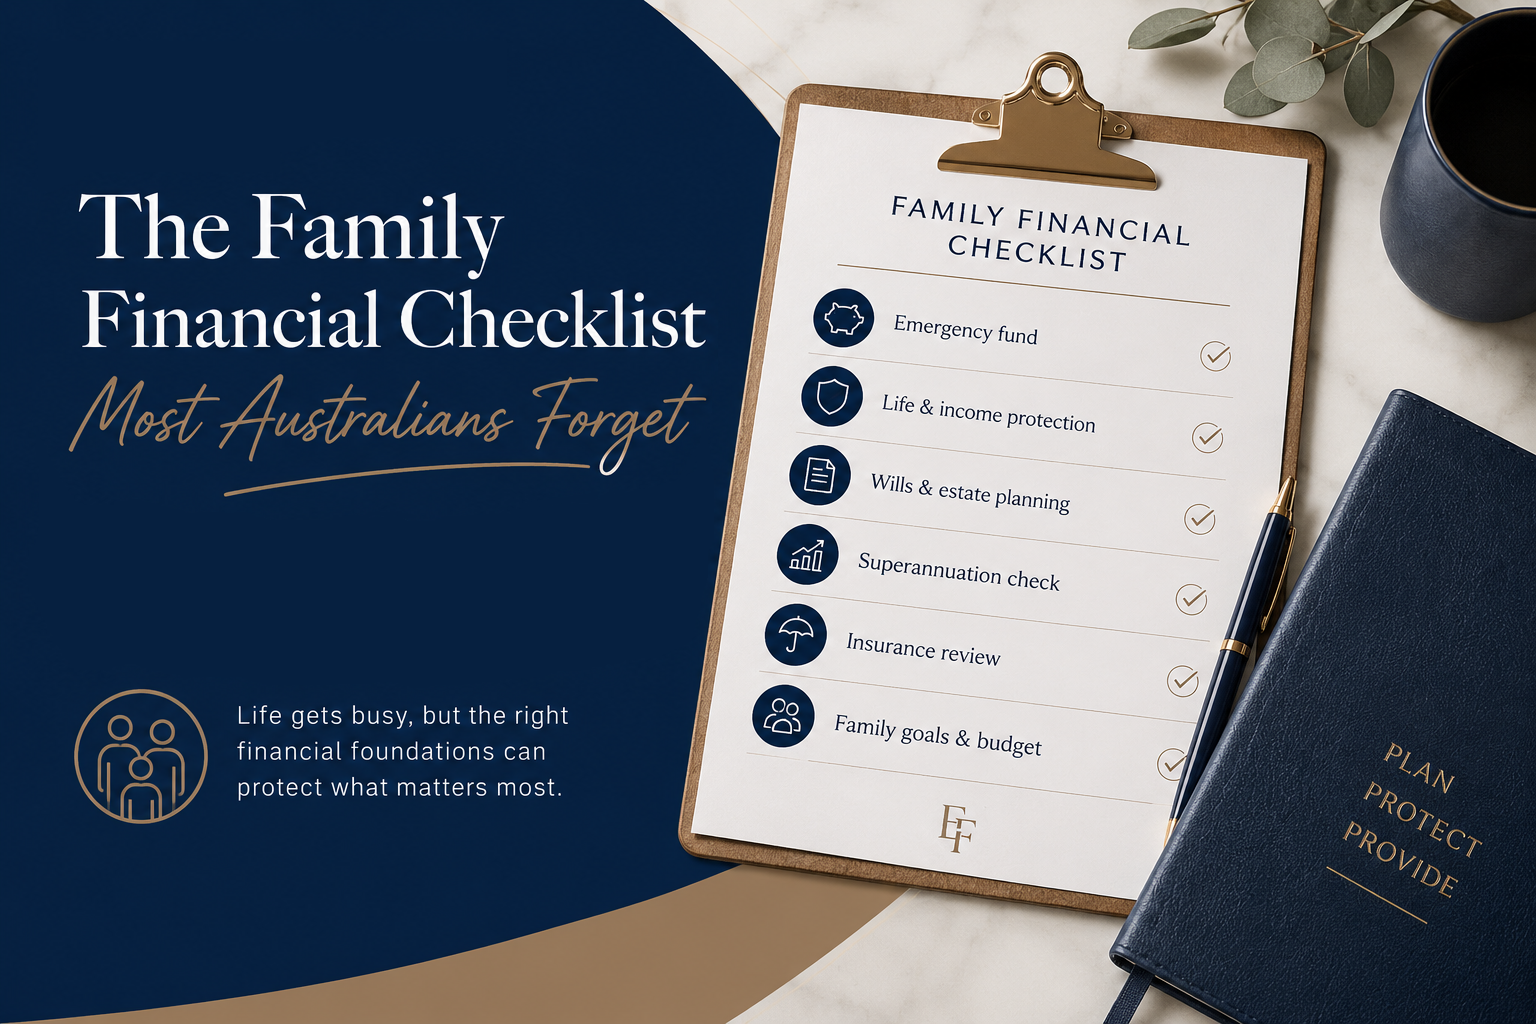
Your broader financial plan might also include:
Cash flow — knowing where your money is going.
Insurance — protecting against larger financial risks that your emergency fund can't cover.
Superannuation and investments — building long-term wealth.
Debt management
— making sure your borrowing is structured appropriately.
Retirement planning
— making sure today's decisions don't come at the expense of your future goals.
The aim isn't to prepare for every possible thing that could go wrong.
It's to build enough financial resilience that when something unexpected happens, it doesn't completely derail your plans.
There isn't a magic number
The right emergency fund for you depends on your income, expenses, debt, employment, family situation and overall financial position.
Rather than asking:
“How much should everyone have?”
A better question is:
“How much would I need to feel financially comfortable if something unexpected happened?”
That's a much more useful place to start.
Need help working out where you stand?
An emergency fund is only one piece of your financial picture.
At Elevate Financial Planning, we can help you look at your cash flow, debt, investments, super, insurance and longer-term goals together — so you can make informed decisions about your financial future.
If you're ready for a little more clarity around your finances, get in touch with Elevate Financial Planning.
For personalised
financial services and advice, speak with your
Financial Advisor today at
Elevate Financial Planning
- Arlan Davine (Elevate Financial Planning)